Stock market newsBreaking
ETFs in 2024: Outperfomers, Underperfomers, and Trends
The decline in ETF valuations shows the lack of new buyers, hinting at a broad-based move away from riskier assets.
 Artem KirillovTrading.Biz
Lululemon stock is down 40%, pushing its P/E to the lowest level in seven years. Analysts see a valuation opportunity despite slower future growth.
 Rahul NambiampurathTrading.Biz
The iconic athletic apparel brand has seen its stock decline 40% since the late 2023 all-time high. That is presenting an opportunity. Its Price/Earnings (P/E) is the lowest it has been in seven years.
Trading.biz analyst Cory Mitchell commented “LULU recently hit its lowest P/E in the last seven years at 23.7. After a slight bounce in the stock the P/E is currently 24.9. The last time investors could buy LULU near a 25 P/E was mid-2017.
The company is still steadily growing revenues and analysts are forecasting increasing earnings over the next several years. LULU likely won’t be able to grow at the same pace it has in the past, but the sharp stock price selloff presents an opportunity to pick up a high-quality stock at a fair to very good valuation.”
Despite the recent stock sell-off, LULU is still a quality company. Here are some key metrics to consider.
Lululemon is a quality stock trading at its best valuation in about seven years. There are risks though. The selloff may continue or earnings may slow more in the future than expected. The P/E may continue to drop (or even rise if earnings fall) without the share price rising.
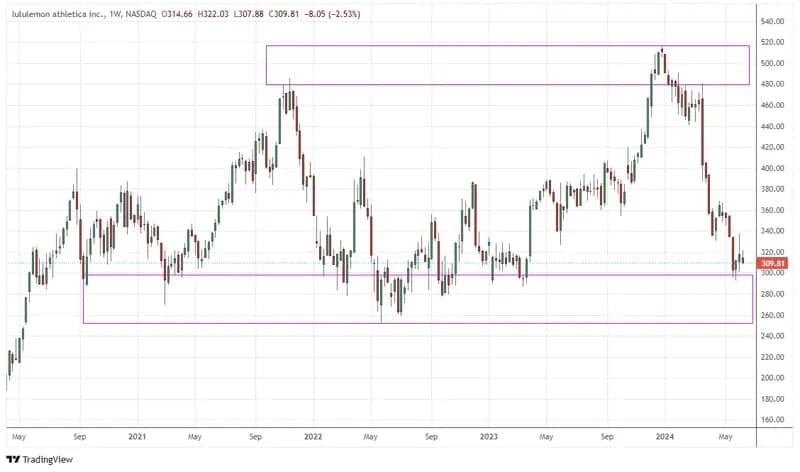
Technically the stock has been in a big range for the last few years. $300 to $250 is the lower end of the range, with $475 to $500 being the upper end of the range. Buying near the low end of the range is technically appealing.
The decline in ETF valuations shows the lack of new buyers, hinting at a broad-based move away from riskier assets.
Artem KirillovTrading.Biz
Trading.biz reports that the S&P 500 hit a fresh high even though most individual stocks remain below their 50-day moving average.
 Semelyuk Alexandra Trading.Biz